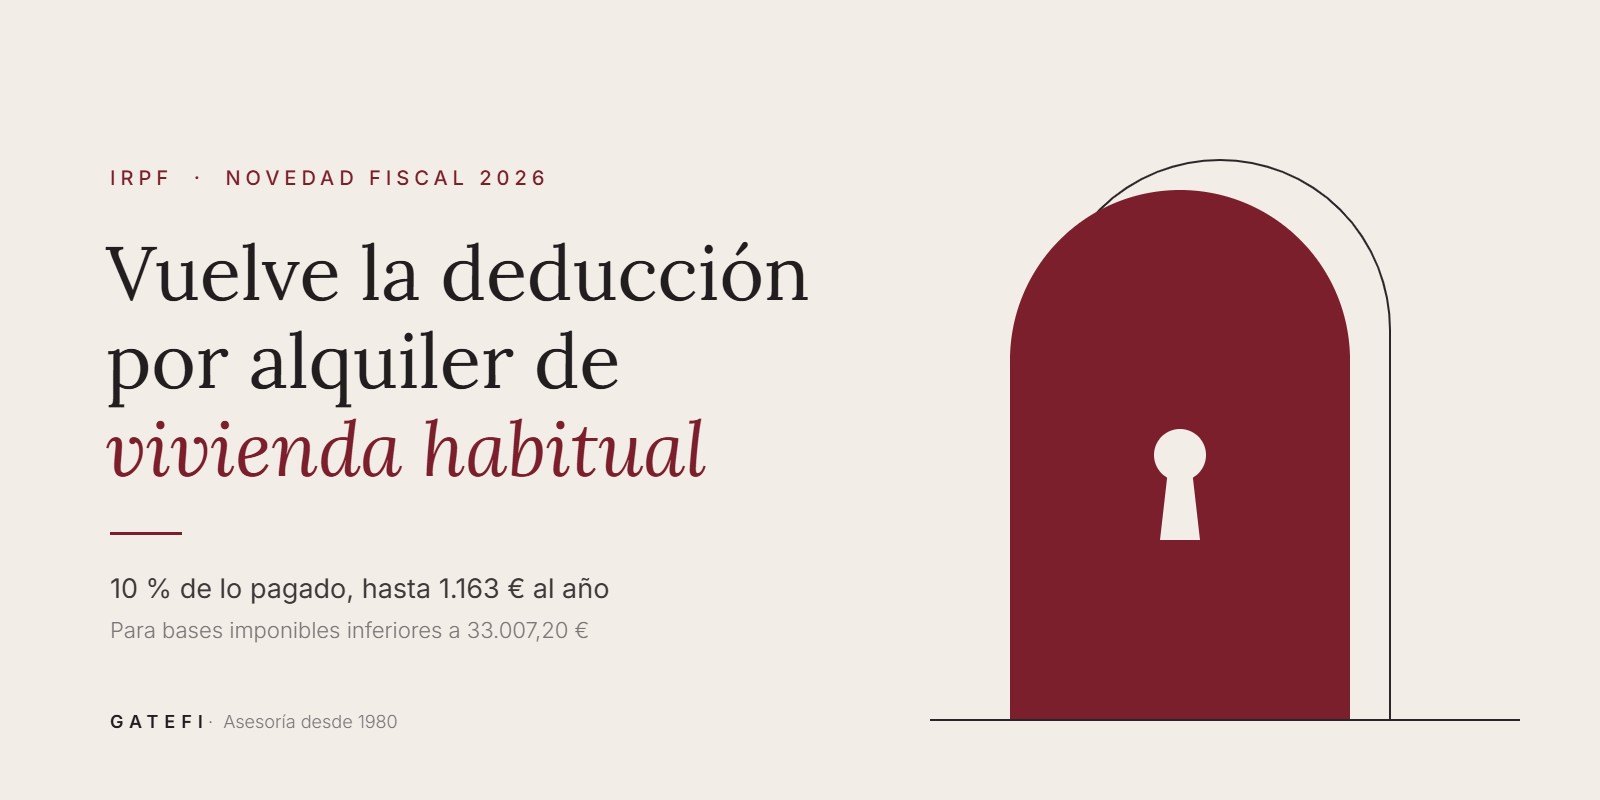
The deduction for renting a main home is back in the state income tax. Tenants with a taxable income below 33,007.20 euros can deduct 10% of what they pay in rent, with a maximum saving of 1,163 euros a year.
It is recovered by Royal Decree-Law 29/2026, of October 6 (BOE of October 7), which adds a new section 6 to Article 68 of the Personal Income Tax Law. Since 2015, the state deduction only existed for contracts signed before that date.
Now it applies again to all contracts, without requiring that the home be in an area with a tight housing market. That said, the rule is still pending ratification, and it’s good to know its requirements before relying on it.
Who can apply the rental deduction?
Taxpayers who pay rent for their main home and meet two requirements can apply it:
- Taxable base less than 33,007.20 euros per year. The total taxable base of the IRPF (general plus savings) is taken, not the gross salary.
- Not having another home nearby. For at least half of the tax period, neither the taxpayer nor any member of their family unit can hold full ownership or a real right of use or enjoyment of another home within 50 kilometers of the rented one.
The second requirement has an exception: that other home doesn’t count if an administrative or court ruling prevents it from being used as a residence.
Also, the regulation talks about full ownership. A minority share in another property (for example, an undivided inheritance with siblings) shouldn’t prevent the rental deduction, unless the rest belongs to your own family unit.
How much can you deduct?
The rental deduction is 10% of the amounts paid during the year, with a cap (maximum base) that depends on the taxable income:
- Taxable income equal to or less than €23,007.20: maximum base of €11,630 per year, which means a deduction of up to €1,163.
- Taxable income between €23,007.20 and €33,007.20: the maximum base decreases linearly: 11,630 − 1,163 × (taxable income − 23,007.20).
- Taxable income of €33,007.20 or more: no deduction.
Examples of calculating the rental deduction
| Taxable baseAnnual rentMaximum baseDeduction | |||
|---|---|---|---|
| 18.000 € | 9.600 € | 11.630,00 € | 960,00 € |
| 28.000 € | 9.600 € | 5.823,37 € | 582,34 € |
| 31.000 € | 9.600 € | 2.334,37 € | 233,44 € |
| 20.000 € | 14.400 € | 11.630,00 € | 1.163,00 € |
In the second case: 11,630 − 1,163 × (28,000 − 23,007.20) = €5,823.37. Since the rent paid (€9,600) exceeds that maximum base, 10% of €5,823.37 is deducted.
Contracts from before 2015 and the new rental deduction
Anyone who rents with a contract signed before January 1, 2015 can still apply the old deduction under the transitional regime (fifteenth transitional provision of the Income Tax Law). What they can’t do is combine the two for the same home and the same year.
The Royal Decree-Law adds a section 3 to that transitional provision: the transitional regime does not apply if the taxpayer has applied the new deduction from Article 68.6 for that property during that period.
In practice, you’ll have to calculate both every year and go with the more favorable one, keeping in mind that the new one has its own taxable base limit.
Another update: rehabilitation aids that aren’t taxed
The same Royal Decree-law expands the public aid that is not included in the taxable base of personal income tax. Excluded are the aids from the line for promoting building rehabilitation, accessibility, and urban and rural renewal under the 2026-2030 State Housing Plan (Royal Decree 326/2026, of April 22).
Validity: pending validation
The rental deduction has been in effect since October 8, 2026, but on a provisional basis. A royal decree-law must be ratified within 30 days of its enactment.
With the Cortes dissolved due to the November 29 elections, it falls to the Permanent Deputation of the Congress. The press places the vote around November 12, without official confirmation.
It’s not just a theoretical precaution: Royal Decree-Law 26/2026, which already included this deduction, was repealed by Congress on October 2.
Also, it remains to be clarified whether in the 2026 Income Tax all of the rent for the year can be counted or only the portion paid since October 8th. nota informativa de la AEAT it includes the measure among those that take effect from the moment it comes into force.
Tips to make the most of the rental deduction
- Keep the rental contract and all payment receipts (preferably by bank transfer or direct debit).
- If your taxable income is around €33,000, start estimating your 2026 tax return. Note: the limit is measured on the taxable income, before deductions, so contributions to pension plans don’t help you qualify for the deduction.
- Check that no one in your household has another home within 50 km.
- If you live in Catalonia, also look into the regional rental deduction, which has its own requirements.
If you want more ideas to pay less on your tax return, check out our consejos para ahorrar en la Renta.
Shall we help you?
At Gatefi we offerasesoría fiscal to individuals, freelancers, and businesses since 1980. If you want to know if you can apply the new deduction and how much it will mean for you, contacte con nosotros, escríbanos a gatefi@gatefi.es, Call us at 93 321 09 00 or send us a WhatsApp at 678 331 691.
Sources: AEAT, principales novedades tributarias del RDL 29/2026; La Moncloa.



Leave A Comment